Monday, June 23, 2008

State vs. anarchy -- the false dichotomy

The false dichotomy between "state" (or "goverment") and "anarchy" can be highlighted every time someone tries to come up with a coherently stated definition of either of these supposed opposites. If we take, for example, Hans-Hermann Hoppe's definition literally, a federalist system of governments like the United States is not a "state" at all, nor are a wide variety of other political systems that have or could exist that could hardly be called "anarchies". Here's Hoppe:
Let me begin with the definition of a state. What must an agent be able to do to qualify as a state? This agent must be able to insist that all conflicts among the inhabitants of a given territory be brought to him for ultimate decision-making or be subject to his final review. In particular, this agent must be able to insist that all conflicts involving himself be adjudicated by him or his agent. And implied in the power to exclude all others from acting as ultimate judge, as the second defining characteristic of a state, is the agent's power to tax: to unilaterally determine the price that justice seekers must pay for his services. [Source]
I'm not trying to pick on anarchists like Hoppe here. Statist political scientists and politicians also oversimplify the world of politics and law with this false dichotomy. This usually takes the form of observing that modern governments have feature X, and by two invalid steps of logic (that X is necessary for government and that without such government there is only lawless anarchy) concluding that anyplace lacking feature X would be a lawless anarchy. "Anarchy" is thus used as a boogyman to justify all sorts of brutality, waste, and other wrongs perpetrated by modern governments.

Let's start here:
This agent must be able to insist that all conflicts among the inhabitants of a given territory be brought to him for ultimate decision-making or be subject to his final review
The United States federal government does not "insist that all conflicts among the inhabitants of a given territory be brought to [it] for ultimate decision-making", nor even that all disputes are "subject to [its] final review." Most disputes occur under State and local law, and the final arbiters of State law are State supreme courts. Only in the minority of cases where a dispute raises a question of federal law, or involves people from multiple states, do federal courts assert jurisdiction. Nor, of course, do States hold an all-encompassing monopoly of power -- many issues instead come under local or federal jurisdiction. Furthermore, federal, State, and local governments all have overlapping powers of taxation.

Now it might be argued that some provisions of federal law, for example in the Constitution, are so ambiguous as to effectively allow federal courts to assert jurisdiction whenever they strongly desire to do so. To the extent that there is merit in this argument, it only creates a conflict of interest because federal courts are able to judge the scope of their own power:
In particular, this agent must be able to insist that all conflicts involving himself be adjudicated by him or his agent.
Hoppe indeed identifies a serious defect in modern constitutions -- they violate the ancient common law maxim that no one should be a judge in his own case. But this defect is readily cured without the kind of radical from-scratch destruction and reconstruction of law and politics that the term "anarchy" suggests. The reforms needed to cure this defect (described in more detail here) are (1) selecting judges by a method completely independent of the other political branches, so that in no real sense would judges and those in other branches that they judge be agents of the same entity, or one the agent of the other, and (2) by reform of jurisdiction, for example by changing who has jurisdiction over constitutional questions. If federal courts were not selected by Presidents and Senates whose power they then judge, and if federal courts reviewed disputes involving state constitutions, and a super-federal court reviewed disputes involving the federal Constitution, so that they did not have final say over the scope of their own power, conflicts of interest of the kind that Hoppe rightly criticizes in modern governments would no longer commonly arise.

What Hoppe is really arguing against can more accurately be called "sovereignty", the idea of one entity with a monopoly over all coercive powers in a territory, than "state" or "government." There are plenty of configurations of coercive power, in fact most such configurations over most of history, that do not involve this kind of sovereignty. In highlighting the problems of sovereignty I quite agree with him, but observe that the United States and many other historical and current polities are or were not "sovereign" in this sense, and many historical entities (such as the system of political property rights over most of English history) were not even close.

Those of us who would like to greatly reduce the brutal and wasteful powers of modern governments do ourselves a great disservice by adopting the statist term "anarchist." Anarchy is the boogyman of statists. A libertarian calling himself an "anarchist" is like an agnostic or atheist calling himself a "Satanist." Seek not for imaginary opposites, but for real alternatives.

Friday, June 20, 2008

Green beards and master genes

There is a sense in which gene expression can be hierarchical: some genes are "master genes" that control the expression of many other genes. In other words, they select which genes to express when. It is thus entirely possible, and indeed in advanced organisms common, for a genome to encode a wide variety of phenotypes, only some of which get expressed, depending on the alleles of the master gene(s), on environmental cues, or both. Master genes can control gender, sexual orientation, and a wide variety of other complex structures and behavioral tendencies encoded for by complex assemblies of genes.

The green beard effect occurs when linked genes produce all three of the following: (1) a signal, (2) recognition of that signal in others, and (3) different behaviors (e.g. altruism) towards those exhibiting that signal. If the genes can remain linked, organisms expressing the green beard allele can cooperate with each other and spread in the population. Most evolutionary biologists, studying the genetic evolution of behaviors in animals, have tended to dismiss green beard effects as rare, because they have only rarely been unambiguously observed in the field, and because it's highly unlikely that genes can remain linked in this manner during sexual recombination.

I strongly suspect that this view is mistaken. It's hard to distinguish green beard from normal ("blue beard") signalling and recognition systems (such as those involved in kin altruism, mother/fetus interfaces, sexual selection, gender recognition, etc.) Green beard effects usually evolve "parasitically" on already existing "blue beard" signalling systems. Both of these make it difficult to recognize green beard effects, because they are usually strongly associated with existing "blue beard" signalling systems. Furthermore, strong linkages are not nearly as rare as has been assumed, because of the existence of master genes that control the expression of many other genes. Alternative alleles of a master gene could, for example, code for the selective expression of alternative strategies encoded in many other genes. In other words, a wide variety of genes, each existing in all members of a species, could code for two or more complex strategies, with a master gene coding for which of the strategies actually gets expressed.

Nature provides a great example where I believe a master green beard gene is at work: the side-blotched lizard. The male lizards have three different strategies for defending mates: dominance, sneakiness, and cooperative mate guarding. Violating standard theory, these sexual strategies correspond to very distinct throat color patterns: orange, yellow, and blue. Orange-throated lizards dominate a mate and territory and don't cooperate with other males in this task. Yellow-throated lizards look and act like females, and sneak around cuckolding orange-throated lizards. Blue-throated lizards cooperate to detect and fend off yellow lizards, but are weaker and can be defeated by yellow-throated lizards. The result is
a kind of "rock-paper-scissors" game, where orange defeats blue, blue defeats yellow, and yellow defeats orange. The result is an evolutionarily stable situation in which no single color morph can dominate the population...

The remarkable thing about the color morphs of side-blotched lizards is that an enormous range of behavioral, physiological, and life-history traits are correlated with throat color. Genes for different traits can be linked physically if they occur close together on a chromosome, but according to [evolutionary biologist Barry] Sinervo, throat color is linked to far more traits than could possibly be physically linked on the same chromosome.

It's almost as if the whole genome is tightly tethered to this one master locus," he said. "In order to be a really 'good' blue, you have to have all these other alleles [of different genes] lined up in the right combination, and the same is true for orange and yellow color morphs. So there is strong selection for these different fitness combinations.

"The whole genome crystallizes into three types," Sinervo said. "The alleles for all these different traits should be independent and separated on the chromosomes, yet the genes are interacting through this one locus."
The lizards, the throat color gene determining orange, yellow, or blue throat splotches seems to be tightly correlated to the rest of a distinct complex strategem. This is inexplicable by traditional arguments against the green beard, which assume that the alternative strategies are coded in three separate sets of alternative alleles, all of which must be expressed to work. Being broken up and recombined every generation, they cannot stably evolve as distinct and competing sets of genes. But the cooperation of the blue-throated lizards qualifies as a green beard effect, bringing this assumption into question. The linkage of throat colors with complex behavioral strategies can be readily explained if all three strategies are encoded in all male side-blotched lizard genomes, and there is only one strong linkage, that is between the throat color gene and a gene that controls the expression of many other genes. Indeed, I wouldn't be surprised if the throat color gene and the master gene were the same gene.

There are strong adaptive reasons for master genes to control complex assemblages in this way. Behavioral strategies, and indeed structures and metabolic pathways, that are too complicated but not ubiquitous in a breeding population are encoded across too many unlinked genes. As a result they cannot survive sexual recombination. All advanced multi-cellular organisms thus have master genes or distinct chromosomes that control the expression of many other genes. In the case of gender, distinct chromosomes are usually involved, but master genes can behave similarly, producing small sets of complicated strategies, each strategy very distinct from each other and each a distinct alternative to the other. In information theory terms, there is a large information distance between each of the alternative strategies, just as there are many differences between the genes expressed in the development of a female versus those expressed in a male. A wide variety of distinct morphological and behavioral traits are bundled into a small number (in the case of genders, typically two) of alternatives. A wide variety of other genes encode the distinct complex structures or strategies, to be invoked by master genes, developmental stages, and environmental cues. Since the complicated parts of each strategy are encoded in every member of the breeding population, there is no problem with sexual recombination breaking linkages between many genes encoding each strategy: each gene of each strategy is still there waiting, in the next generation, to be invoked by the master gene.

I strongly suspect that master genes and green beard effects analyzed in this manner will shed light on a wide variety of puzzles in evolutionary biology, including sexual selection, sexual orientation, and racial and ethnic preferences that, under the assumption that green beard effects are not important, have long defied analysis or been assumed to be purely environmental.

Monday, June 09, 2008

Commodities, currencies, and the St. Petersburg paradox

Hal Finney describes the surprising results of the Hotelling model of nonrenewable commodities:
prices become much higher than the costs to produce the resource, the opposite situation from competitive markets in other kinds of commodities. Yet resource owners restrain production without the need for a cartel or any coordination.
This occurs because, under the Hotelling assumptions that the commodity is not renewable and cannot be substituted for (and of secure property rights, as David Friedman correctly points out) the commodity producer can choose between producing today or keeping it in the ground to produce tommorrow, with no fear of permanently losing sales to some competitor. Any sales lost to a competitor today draws down the competitor's fixed stores and can be recouped at any time in the future.

What the Hotelling model does not properly account for is that these very characteristics also make these goods great substitutes or hedges for money. Hotelling looks at a "fixed" or "prevailing" interest rate, but we should really be looking at expectations of future interest rates, taking into account expectations of future inflation. And we should account for changes in these expectations. If we do so, I think we will find the model to have high explanatory power (albeit not high predictive power, since we can't outguess the market about future monetary conditions -- but the search for predictive as opposed to explanatory power in economic models is largely futile anyway).

Imagine a world with two currencies C1 and C2 and two nonrenewable minerals, M1 and M2. C1 money supply outstrips money demand by 10%/year, and for C2 by 5%/year (in other words, C1 "inflates" or "falls" by 10%/year and C2 by 5%/year). If the price has not properly increased to account for future expected inflation, people will prefer holding M1 and M2 to holding either of the currencies. They will play "hot potato" with the currencies: as soon as they obtain a currency in trade, they will try to purchase M1 or M2 with it. All holders of M1 or M2 will demand a stiff premium to exchange their minerals for falling currencies. What premium will they charge? In theory, the inflation premium is infinite: it is a "net present value" calculation of the depreciation of the currency into the infinite future. In practice, (as with the St. Petersburg paradox, and because no commodity is perfectly nonrenewable or perfectly immune to substitution over the long term), the premium will just be very high: not only far higher than the cost of production, but also far higher than the Hotelling model under the assumption of no inflation. Inflation expectations will dominate the prices of M1 and M2 in C1 and C2.

Now imagine that inflation expectations change. If expectations of inflation in C2 to infinity go down from 5% to zero, we have in theory a change of net present value of revenue streams from M1 and M2 in currency C2 from infinity to zero, and in practice just a very high drop. It takes only a small change in inflation expectations to send the prices of M1 and M2 in C1 and C2 soaring or plummeting.

Since the standard Hotelling model predicts no abrubt price changes, and the monetary model does, the monetary model is a better choice for explaining the actual dramatic price movements in relatively nonrenewable commodities such as oil that we have observed.

Under imperfect information, since we have far better information about geology and technology than we do about future monetary conditions, and since uncertainty in monetary conditions produces far greater price changes than uncertainty about geology and technology, we can again conclude that abrupt changes such as we've seen are due almost entirely to changes in monetary expectations rather than in "fundamentals".

Furthermore, when we see dramatic changes across a wide variety of commodities, being led by the less renewable commodities like oil, Occam's Razor (or equivalently, basic probability) tells us that there are not 100 different explanations for why 100 different commodities have all gone up dramatically. Rather, we need only two quite related explanations: changes in inflation and inflation expectations for the currencies they are priced in.

Two commodities that come relatively close to being Hotelling nonrenwable commodities are gold and oil. For gold, the above-ground stockpiles are far greater than the annual production. For oil, the below-ground stockpiles are far greater than the annual production. The price of gold has always historically been dominated by its role as money, monetary substitute, or hedge, or equivalent, and the price of oil is also coming to be so in an age of floating currencies and in the current decade of rising inflation expectations. When we realize that Hotelling nonrenewable goods make better long-term stores of value than less renewable commodities, we can explain why, while all commodities have dramatically risen over the last three years, the surge in oil has been disproportionately dramatic, and even more dramatic than the rise of gold: the rise in oil combines an increasing use of oil as an inflation hedge (mostly by the producers themselves curtailing production), which effects oil but not gold (which has long been used this way), with increasing inflation expectations (which effect both gold and oil, and other commodities to a lesser extent).

It is often noted, in rebuttal to the theory that the falling dollar is mostly responsible for commodity price rises, that the dollar has fallen less gainst the euro, or against a basket of other currencies, than oil and many other commodities have risen in dollar terms. In other words, oil and most other commodities have also risen in euro terms, just less so. There are a number of problems with this argument as a way of dismissing monetary causes.

The first problem is that these statistics only record falls relative to other currencies. It assumes there is some currency out there, or some basket of currencies, that is a stable standard of value that we can measure against. But there isn't. It's quite possible, and indeed currently quite probable, that the euro etc. supply has also inflated (relative to demand for the currency), so that all major currencies are falling relative to a hypothetical stable standard of value. They are just falling by on average less than the dollar is falling. Just because there is no standard to measure them against doesn't mean they can't collectively fall (or equivalently, that they can't all collectively inflate, as defined by greater supply, less demand, or both for the currency).

Also important is that the euro is too new and untested by time, and other currencies too small, for them to make good substitutes for the dollar. So when the dollar starts becoming dodgy, people turn to commodities to hedge debt denominated in unreliable currencies (which currently means practically all debt -- not just "junk" debt). So we have three monetary factors each causing commodity prices in dollars to rise:

(1) More dollars chasing the same (in the short term relatively inelastic) supply of commodities. This directly effects only the dollar prices.

(2) Greater demand for commodities as a substitute or hedge for currency-denominated debt, to hedge against further possible inflation. Small changes in inflation expectations, as discussed above, can have large impacts on commodity prices. This increases commodity prices in all currencies.

(3) A flight to safety from the credit crunch, creating more demand for safer forms of debt (e.g. U.S. Treasuries), and thus even more demand for commodities to hedge the currency risk from holding that debt. This increases commodity prices in all currencies.

No "manipulation" or irrational "speculation" is required to explain commodity prices, and there may not even be a bubble (although a bubble could easily arise under such conditions of high uncertainty). Rising commodity prices, and in particular the disproportionate surge in oil, are mostly or entirely just a rational and efficient response to the poor state of the world's floating currencies and the credit crunch.

(This post is based on previous comments I have made at other blogs, including in response to Hal's post linked to above).

U.S. Supreme Court breathes new life into first sale rule

The United States Court of Appeals for the Federal Circuit, which usually has the final say on most U.S. patent appeals, and thus the most influence on the development of U.S. patent law, has recently been eroding conservation of rights, the principle that you cannot sell or claim more than you own, and in particular that you can't reclaim it once you sell it. Under the patent exhaustion rule, which is as old as patent law itself, patent rights are exhausted upon the first sale of an object embodying the patent. The patent holder is effectively allowed to sell the patent rights once per object, rather than maintaining control shared control over the object with the object's owners and possessors through its entire lifetime. The patent holder is allowed to collect a royalty only once per object. Once the first sale occurs, the object reverts from being held in a tangle of intellectual property, with a potential wide variety of "owners" imposing a wide variety of restrictions, to being owned outright by a single person or express partnership as traditional (i.e. real or personal) property.

The Federal Circuit has eroded this principle in a number of ways: by ignoring foreign sales (so that for example an object first sold in Canada under a Canadian patent, then imported into the U.S., comes under the thrall of the equivalent U.S. patent), by excluding certain kinds of patents from the rule, and by changing the default rule for implied licenses (i.e. ruling that the default implication was that resale was not allowed, effectively extending patent rights beyond the first sale), etc. In some cases patent rights seem to disappear, but then reappear later on in the lifetime of the object. In other cases the patent holder maintains a continued shared control of the object over its entire lifetime, despite any changes of normal ownership and possession over the object.

The Supreme Court today in Quanta Computer v. LG Electronics reversed, 9-0, the erosion of the first sale rule via change of default rules and via the exception of certain kinds of patents. LG Electronics had licensed its patents to Intel, and Intel sold chips it made using that technology to Quanta, and LG sued Quanta for infringement. The Supreme Court held that all kinds of patents are covered by the first sale rule, and that the default (implied) patent license terms assume no further rights of the patent holder over the object:
The authorized sale of an article that substantially
embodies a patent exhausts the patent holder’s rights and
prevents the patent holder from invoking patent law to
control postsale use of the article. Here, LGE licensed
Intel to practice any of its patents and to sell products
practicing those patents. Intel’s microprocessors and
chipsets substantially embodied the LGE Patents because
they had no reasonable noninfringing use and included all
the inventive aspects of the patented methods. Nothing in
the License Agreement limited Intel’s ability to sell its
products practicing the LGE Patents. Intel’s authorized
sale to Quanta thus took its products outside the scope of
the patent monopoly, and as a result, LGE can no longer
assert its patent rights against Quanta. Accordingly, the
judgment of the Court of Appeals [Federal Circuit] is reversed.
LG Electronics thought it could restrict subsequent use of the chips, and indeed had a cause of action directly against subsequent users of the chips (e.g. Quanta), via its license agreement with Intel. The Federal Circuit agreed with this pathological reasoning, but the Supreme Court shot them down:
LGE points out that the License Agreement specifically disclaimed any license to third parties to practice the patents by combining licensed products with other components. But the question whether third parties received implied licenses is irrelevant because Quanta asserts its right to practice the patents based not on implied license but on exhaustion.
Imagine Alice could make a contract with her friend Bob which gave Alice the right to confiscate things that you or anybody else bought from Bob. If property rights would be confiscated from third parties by contract on ad-hoc basis, there would be no effective property rights. Contracts should never be able to impose duties on third parties. Only property law (via deeds, licenses, etc.) can impose duties on subsequent owners or licensees, and these transactions should strictly adhere to conservation of rights and intellectual property exhaustion if they are not to interfere with others' property rights.

For property deeds to impose duties on subsequent owners, they must either be clear from the object itself (e.g. a physical object is obviously personal property clearly belongs to somebody) or they must be clearly written and publicly recorded (e.g. liens on personal property, real property deeds that define property boundaries and restrict use of the property, etc.) Furthermore, there should generally be one set of restrictions based on one owner per object, or simple and well-known variations on that (e.g. joint tenancy), not a wide variety of restrictions stemming from a wide variety of people who "own" the object in different ways, i.e. intellectual property owners. An intellectual property license, when as here is not clear, should be construed to follow the default rules of intellectual property law, especially those rules like patent exhaustion that preserve a standard sphere of traditional property rights not entangled in a web of intellectual property.

My kudos go out to our highest court for defending traditional property rights against further erosion by the Federal Circuit's pathological interpretations of intellectual property law.

Here is Dennis Crouch's take on the case.

Wednesday, June 04, 2008

The war against retirees

I am quite chagrined that a number of influential folks have almost reached the same conclusion as I, namely they've concluded that "speculation" not fundamentals are driving most of the recent commodities rise, yet they reach a policy conclusion that is utterly insane: restrict or ban much of this "speculation". They stop at the word "speculation", repelled in horror by the idea, and don't take it a step farther -- ask why this "speculation" is going on. A good clue comes from those responsible for the biggest piece of it -- retirement funds. Retirement funds have long been heavy, relative to other kinds of funds, on less volatile (over <15 year periods) investments like bonds. But bonds are mostly denominated in dollars. With the threat of dollar inflation (apparent from the recent drop in the dollar, from recent Fed activity, and from the history of the floating dollar in the 1970s) they have a fiduciary responsibility to protect their investors' retirement nest eggs by hedging bond positions with commodities baskets. And that is just what they have been doing. Besides providing an inflation hedge and a performance comparable to bonds since the dawn of the floating dollar era in 1970, commodities are also "anti-correlative", i.e. they tend to move in the opposite direction of stocks and bonds, substantially reducing the risk of the overall portfolio. To suggest that commodities are not proper vehicles for investment in this era of the floating dollar is stunningly pathological, but that hasn't stopped a number of people who should know better from suggesting this.

(I suspect a similar explanation is behind much of the high Chinese demand -- but that rather than buying futures they are actually stockpiling commodities, including cutting back on production of the mineral reserves that they own, to hedge their peg to the U.S. dollar, their massive dollar earnings from exports, and their heavy investments in U.S. Treasuries, all of which are vulnerable to dollar drop or inflation -- but I don't know where data on such stockpiling activity might be readily available).

Many of these retirement funds can be politically influential. I wish, for the sake of the retirees they have a duty to protect, they would defend themselves politically against the insane proposals to restrict or ban commodity index funds. Those seeking to save for retirement have perfectly good and strong reasons for investing in commodity indices: they don't want to see their retirement funds eroded away by inflation, as happened to millions of seniors in the 1970s. More generally, people have a right to be free from ignorant government interference and federal spite when they choose to hold their savings in forms protected from the erosion of the dollar.

Commodity index exchange traded funds (ETFs) have allowed people to construct, without many of the costs, risks, and complexities of direct purchases of commodity futures, retirement portfolios hedged against inflation. Portfolios protected against inflation are an exceedingly valuable asset both for the retirees and for the society on which said retirees will be less dependent. They are also quite valuable for many other kinds of investors, such as college endowments that lower the cost of tuition for future students and fund research that benefits the future of us all. Instead of attacking the fever by shutting down the immune system, i.e. instead of attacking the commodities indices needed to hedge against inflation, it is the prior main cause of the problem, Federal Reserve monetary policy, that needs to be addressed. The Fed needs to put a higher priority on preserving the value of the dollar and fighting inflation, and it needs to use leading indicators (e.g. commodity and foreign exchange prices) far more than trailing indicators (e.g. CPI, PPI) in this task. (I understand of course that the recent credit crunch has probably been a very good reason for the Fed to "print dollars." That doesn't change the fact that the Fed is smack dab in the middle of the causal chain that has led to the commodities boom, and that savers have a right, and investment funds a fiduciary duty, to protect their savings against the inflationary effects of Fed policy).

It's certainly possible that some of the commodities boom is a bubble. It is often the case that economically efficient bull markets become overextended into wasteful bubbles, it being very hard to tell just how large of a price increase is actually warranted, and we may be seeing some of that now. (These bubbles are allowed to occur by a lack of available instruments for speculation, especially the transaction costs involved in holding long-term short positions against markets that may rise substantially further before they fall. The worst way to combat a bubble is to ban the last modicum of imperfect speculative mechanisms such as short sales that currently prevent bubbles from getting worse). There is no easy way to gauge just how much retirement funds and others seeking to hedge inflation need to allocate to commodities baskets in order to optimize their portfolios, because it depends greatly on future Fed behavior. On the one hand we know that hyperinflation has sometimes occurred historically with floating currencies, so that dramatic further increases in commodity prices are possible; on the other hand the farther commodity prices go up (and they have gone up very far indeed) without corresponding inflation in other goods and services, the more downside price risk there is in commodities. Oil next year might be $40 per barrel, or $300 per barrel, or anything in between. It's certainly true that commodities have become a far riskier, i.e. more volatile, investment than they were three years ago, and that puts a severe limit on the proportion of an investment portfolio it makes sense to devote to commodities. But that proportion is certainly nowhere near zero as the lunatic anti-"speculation" activists would have it.

(This post is based on a comment I made on a previous post. Here,, h/t to reader "munin", is a hedge fund guy who reaches almost the right theory, but the abominable policy conclusion, and is the source of the graph above. Here is some of my previous writing on this subject: The Monetary Value of Liquid Commodities and Commodity Derivatives: The New Currencies).

[Update: at least we don't have war hysteria (or click to enlarge the facsimile at left). Note that Herber Hoover, who many history books still proclaim with preposterous prevarication to have been a free market guy, and who later presided over the start of the Great Depression, was at this time (1917) the head of President Wilson's Food Administration, which came up with this plan for "Control of Food By Government". Hoover's food plan, like the crazy plans to "fix" the commodities markets today, was designed by and for the ignorant and the paranoid, targetting "Evils" of "Unreasonable Profits, Speculation, and Hoarding", i.e. the "evils" of people stocking up to ensure own and their customers' future food supply instead of letting the benevolent Herbert Hoover control it for them. Today it is apparently evil to protect your retirement nest egg instead of letting it fall with the dollar].

Thursday, May 29, 2008

The Coase Theorem is false: contracts depend on tort law

In the Rothbardian ideology of anarcho-capitalism, all law can supposedly be derived from contract, the entry into which is supposed to be voluntary. "Social contract" theories of government also tend, by this euphemism, to suggest that the formation of governments was somehow voluntary, an idiotic idea that anarchists such as the legal scholar Lysander Spooner have easily debunked.

David Friedman justifies his neoclassical version of anarcho-capitalism by the Coase Theorem, which translated into legal terms is usually understood as the following: in the absence of transaction costs, and regardless of the prior allocation of legal rights, any tort ("externality" in economic terms) can be resolved by voluntary bargaining to form a contract, resulting in an economically efficient outcome.

Here are some places where Friedman relies on the Coase Theorem:
Consider two [legal protection] firms with somewhat different customer bases, bargaining over what court's legal system to agree on. Firm A prefers one legal system, say one that permits capital punishment for murder. Firm B prefers a different system, one that does not permit it.

Each firm estimates the value to its customers, and from that the increase it can expect in its revenues, if it can provide them with its preferred legal system. We expect, along conventional Coaseian lines, that they will agree on the system that maximizes their combined benefit. [Source].

A still more attractive and more likely solution [to avoid war] is advance contracting between the agencies. Under this scenario, any two agencies that faced a significant probability of such clashes would agree on an arbitration agency to settle them-a private court. Implicit or explicit in their agreement would be the legal rules under which such disputes were to be settled. Under these circumstances, both law enforcement and law are private goods produced on a private market...

Readers familiar with the economic literature on efficiency may notice that my argument owes more to Coase than to Marshall. I have relied on the idea that parties will negotiate towards efficient contracts, rather than on the conventional analysis of a competitive industry....[Source]

The proof that the Coase Theorem is false is actually quite simple: the assumptions of the Theorem contradict each other. The assumption that transactions are voluntary contradicts the assumption that any prior allocation of rights is possible, including rights that allow one party to coerce another. In fact, for the Theorem to at all make sense, a very large and crucial set of prior rights allocations must be excluded -- namely any that allow any party to coerce another.

But we can't generally solve externalities problems by bargaining under this revised assumption. Externalities cannot be neatly distinguished from coercive acts, as extending one of Coase's own examples illustrates. In this example we have a railroad with a train that, passing by a farmer's wheat field, gives off sparks, which may start a fire in the field. In Coase's account, the prior allocation of rights might give the railroad the right to give off sparks, in which case the farmer must either plant his wheat far enough away from the railroad (wasting land) or buy the right to be free from sparks from the railroad. The prior allocation might instead already give the farmer the right to be completely free from sparks, in which case the railroad can either buy the right to emit sparks from the farmer or install spark-suppressors. If these are the two possible prior allocations of rights, Coase concluded that the railroad and the farmer will in the absence of transaction costs bargain to the most economically efficient outcome: if it costs less for the railroad to reduce the sparks than for the farmer to keep an unplanted firebreak, bargaining will achieve this outcome, and if the reverse, bargaining will achieve the reverse outcome, regardless of whether the farmer initially had the right to be free from sparks. So far, so good -- it seems, on the surface, that if bargaining is costless an efficient outcome will be achieved.

The problem is that these are not the only prior allocations possible. The Coase Theorem is supposed to work under any other allocation of prior rights. But it doesn't. It fails for a large and crucially important class of prior allocations: namely any that allow one party to coerce another. Here's an allocation that may or may not allow coercion, depending on your definition of coercion: a prior allocation that gives the railroad the right to emit as many sparks as it wants. In particular it includes the right of the railroad to emit sparks even if it could costlessly avoid emitting them. Here's one that is fairly clearly coercive: the right to emit sparks even if emitting them costs the railroad something extra (i.e. giving the railroad the right to purposefully emit sparks to start fires even at some extra cost to the railroad). Here's another farther down the coercive spectrum: a prior allocation that gives the railroad the right to torch the farmer's entire field with a flamethrower.

It is usually the case with coercion, as here, that it is far cheaper for the coercer to cause harm than for the victim to prevent it. To increase the threatened harm to the farmer, and thus the revenue it can obtain from extortive bargaining with the farmer, the railroad can spend extra to purposefully threaten the farmer. Here, it is likely far cheaper for the railroad to install a super spark emitter, or a flamethrower, than for the farmer to defend his fields from these sources. Indeed, since any prior allocation is possible, why stop with the farmer's fields? Another possible allocation would give the railroad a right to torch the farmer's barns, and his house, to kidnap his children -- any prior (ex ante) set of rules is supposed to be possible. In turn, if the ex ante rules allow, the farmer could threaten to tear up the railroad tracks or sabotage them to derail the trains. Under all these prior allocations of rights that allow coercion, the railroad need not just bargain to avoid the costs of supressing its externality (whether sparks or flamethrowers), nor need the farmer bargain just within this artificially voluntary spectrum of possibilities that Coase and his followers assume. Instead, if the ex ante rules so allow the railroad and farmer will bargain to avoid a negative-sum outcome: harm to the farmer with no direct benefit to the railroad, or vice versa. Since there are substantial ex post benefits to one party from extorting payments from the other, the party that can threaten the most harm at the least cost to itself has, if the ex ante rules allow, a strong economic incentive to engage in such coercion. These negative-sum games of coercion and extortion lead to highly inefficient outcomes, and they can only be avoided by carefully crafting the ex ante rules to avoid such coercion and extortion. These coercive threats that make negative-sum games possible, and that decrease the payoffs of positive-sum games, cannot be neatly distinguished in practice from innocent externalities: any act or omission of one party that harms another, i.e. any externality, doubles as a threat, whether a tiny threat or a large threat, from which an extortion premium, its size depending on the size of the threat, can be extracted.

In order to try to distinguish coercion, and the extortion it gives rise to, from an "innocent" externality that can be cured by efficient bargaining, there are ways to exclude some of these extreme possibilities from the prior allocation of rights. And indeed criminal and tort law do this: they distinguish purposeful behavior from negligent, and negligent from the mere unfortunate accident. But any such ex ante distiction contradicts the claim that the Coase Theorem applies to any prior allocation of rights. Voluntary bargaining cannnot give rise to tort and criminal law. Quite the opposite is true: at least a basic tort law is necessary to make voluntary bargaining possible. Tort law (and the associated property law which defines boundaries for the tort of trespass) is logically prior to contract law: good contracts depend on good tort and property law. Without a good tort law already in place, nobody, including the "protection firms" posited by anarcho-capitalism, can engage in the voluntary bargains that are necessary for efficient outcomes.

This is not to claim that the polar opposite of anarcho-capitalism must be true, i.e. that "the government" along the lines we are familiar with is necessary. Instead, a system of political property rights that is unbundled and decentralized is possible, and may give rise to many of the benefits (e.g. peaceful competition between jurisdictions) promised by anarcho-capitalism. But political property rights are not based on a Rothbardian assumption of voluntary agreement -- instead, in these systems the procedural law of political property rights, as well as much of substantive property rights and tort law, is prior to contract law, and their origin necessarily involves some degree of coercion. Political and legal systems have not, do not, and cannot originate solely from voluntary contract. Both traditional "social contract" justifications of the state and the Rothbardian idea that contracts can substitute for the state are false: in all cases coercion is involved, both at the origin and in the ongoing practice of legal procedure. In both cases the term "contract" is used, implying voluntary agreement, when the term "treaty", a kind of agreement often forced by coercion, would far more accurately describe the reality. The real task for libertarians and other defenders of sound economics and law is not to try to devise law from purely voluntary origins, an impossible task, but to make sure the ex ante laws make voluntary bargaining possible and discourage coercion and extortion (by any party, including political property rights holders or governments) as much as possible.

Saturday, May 24, 2008

Off-the-shelf seasteading

Every year millions of people spend days or weeks on cruises, but Patri Friedman, Wayne Gramlich, and their fellow Seasteaders want to live on the sea full time. They want, essentially, to conduct political experiments in mobile communities as free as possible from sovereign jurisdictions. To do this, they are designing extravagant new kinds of structures that they believe will withstand the violent storms and other harsh conditions that can occur offshore.

Besides tourism and jurisdictional arbitrage, there are a variety of other economic incentives to live on the ocean. Fishing and fish processing often involve employees spending many months at sea. Oil, diamonds, and soon a wide variety of other kinds of minerals are increasingly being extracted as land-based minerals are slowly depleted.

Gramlich and Friedman have a very admirable goal but are trying to do too many things in parallel. They seem to have spent far more time in creating futuristic designs from scratch than in figuring out how to retrofit normal ships or mobile offshore oil platforms. On top of this is their important but novel and ambitious political experiment in lowering exit costs. While there are some relationships between the politics and the engineering, a better approach is to innovate in one area at a time. Design novel offshore technology, or design novel offshore communities, but don't try to do too much of both at once.

Friedman voices a complaint, hardly uncommon in the world of engineering, that he has a hard time communicating with ocean engineers. I suspect the problem is that Friedman and Gramlich have taken their designs, whether workable or not, far away from the kinds of designs ocean engineers are used to analyzing. If they just started with normal ships and offshore platforms, then used such equipment as building blocks for larger structures, rather than trying to reinvent ocean engineering from scratch, they would not lack for experienced engineers to understand their designs and shops to assemble them.

Sure, such structures seem crude and inefficient compared with the elegant and optimal structures that might be designed in theory. But they would be a far less expensive way to demonstrate the political and economic viability of seasteading. And they could be shown to offshore engineers who could quickly recognize most major problems they might have. The Friedman/Gramlich approach excites the imagination, but a far more incremental approach is needed to make it work. To take up Friedman's analogy: if all that exists are military planes, and you want to start the first civilian airline, don't try designing civilian planes and civilian airports from scratch. Just buy a bomber, yank out the bomb bays and guns, install passenger seats, get permission to use a couple military airports, take a few test flights, and start selling tickets. The first version may well fall very short of the optimal or ideal you have in mind, but it will give you the experience and the revenue needed to improve the design and approach that optimal.

The biggest technological hurdle to meeting the requirements of the political experiment is probably the ability to join and separate the floating platforms at low cost. They must be moored and yet withstand the harshest storms (or alternatively to anticipate the storm, quickly unmoor, ride out the storm separately, and remoor when normalcy returns). This problem is mentioned briefly here but as far as I know, Seasteaders have not come up with a good solution for it.

Mooring in rough water is a hard problem -- there are good reasons docks lie in sheltered bays. Ship-to-ship refueling, a common naval procedure, has long been very dangerous in bad weather. Ships and platforms loosely moored with cables can easily collide, smashed together by wind and wave, with devastating consequences. Friedman and Gramlich believe that their ideal platform will have "no" bobbing, lateral movement, or tilting from waves and wind. But oil platforms do exhibit enough such movements that trying to keep them moored together with traditional techniques in a storm would be highly dangerous. Cables could not prevent the platforms from colliding with high force, whereas a completely rigid mooring that coupled the movements of all the joined platforms would likely fail from strain.

Some good old Internet searching digs up the fact that folks in the deep sea oil and liquified natural gas (LNG) industries have solved a similar problem -- how to offload fluids offshore, from FPSOs to tankers or from tankers to offshore pipeline terminals. For example the LNG industry needs to be able to hook up the huge LNG tankers to the offshore offloading terminals even in storms. One solution to this is the soft yoke flexible mooring. This is often abbreviated "SYMO" for "soft yoke mooring and offloading". It allows ships to moor to each other without the dangers of approaching and colliding in rough wind and water.

A soft yoke flexible mooring (SYMO) for yoking ships together, even in rough waves and most storms. The design allows each ship to ride the waves separately, greatly reducing the strain on the yoke, while keeping them from approaching or dispersing.

Here's how I might do an experiment in offshore political mobility using off-the-shelf equipment or minor variations on same (this "mixed" version, as the Seasteaders would call it, is not terribly original to me, except for including a workable mooring technology):

(1) Get a few dozen yacht owners to participate as volunteers. ("Yacht" here just refers to any seaworthy boat capable of mooring to other such craft and to larger platforms with SYMOs).

(2) Set up a system of two or more privately owned offshore anchored moorings: tough cable moorings such as those used by large ships in the oil industry (eg FPSOs).

(3) Attach a small old cruise ship or retrofitted oil platform to each anchored mooring. These should be large enough to have most of the infrastructure a small cruise ship would have, and be able to provide basic services to the yachts.

(4) Yachts moor to the larger ship or platform using SYMOs. For oil platforms the SYMOs may have to be heavily modified. Yachts might also moor to each other using SYMOs, but some of the yachts should also be anchor-moored to the ocean floor, unless they don't mind the community drifting.

(5) Yacht owners choose which of the two or more communities they will join.

(6) The cruise ships or platforms that form the core of these communities compete to provide various services, amenities, and political systems.

(7) Yacht owners can either be independently wealthy, or they can make a living by providing services to nearby fishing fleets, fish processors, offshore oil platforms, etc., or by providing temporary quarters for workers of same.

(8) When a storm comes that may be too much for the small SYMOs to withstand, everybody gets on yachts and disperses until the storm blows over.

These communities would look a bit like this offshore floating dock in a sheltered bay near Lund, British Columbia -- but much farther offshore, larger, more robust, and more politically independent.
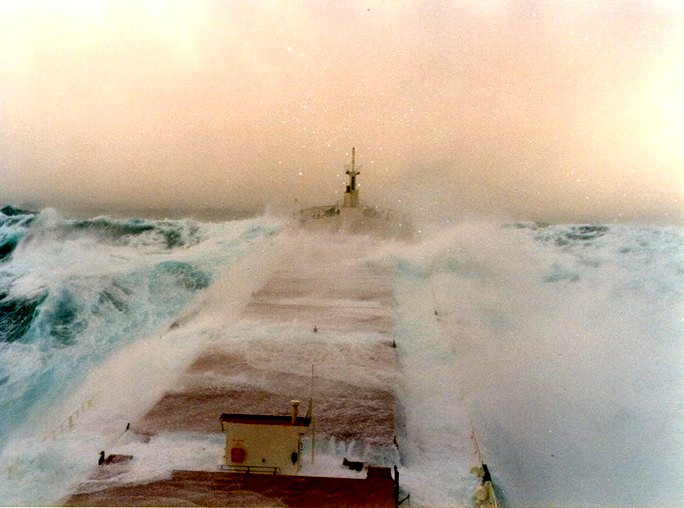
If you see this coming, scram.

There will be big differences between these salty communities and modern towns. If the local court or zoning board or captain-of-captains won't approve improvements to your yacht, or your desire to set up a gambling house or a stinky fish processing plant, just move your house to another seastead community that will tolerate it. (I suspect fish processors will retain their own separate communities). Low exit costs bring freedom.

One kind of public nuisance that these seasteads may be in special danger of running into is what I call a provocative externality, meaning that besides or instead of being ethically dubious or causing direct harm to the community, they may cause danger to fellow community members by provoking a country to attack the seastead: drug smuggling, money laundering, polygamy, being a haven for terrorists, and so on are examples of activities that could, whether rightly or wrongly, provoke attack. Since many of these activities might also be quite lucrative, the political issues of whether to ban them may cause great tensions. Vulnerability to attack by traditional countries limits the degree of substantive liberty seasteads can achieve -- they will not be able to achieve a perfectly voluntary society within even the substantive law, much less within procedural law, which I now turn to.

The political and legal designs for Seasteads need even more work than the engineering designs. It is not enough to just say that all law be based on contract and thus all will be fine. One must rather tackle crucial issues such as legal procedure. As I have written elsewhere, in response to a claim that Seastead government will not be based on coercion:
No coercion? In these Seasteads, who does the law enforcement, and who or what gives them the right to commit law enforcement acts that are physically equivalent to torts and crimes? What distinguishes arrest from assault and battery, imprisonment from kidnapping, legal distraint of goods from theft, or a legal search from trespass? I think you will find that these societies will have to deal with the very same problems of coercion and procedure as our own governments. Calling a legal document that defines and allocates rights to commit these coercive acts a "contract" instead of a "constitution" may be the Rothbard-correct way to do things, but it doesn't actually go very far towards solving the hard problems of living together in a world where people are often coercive.
It is even more important for the political and legal designs than it is for the engineering designs to take an off-the-shelf approach. Pick a country and subdivisions thereof, either a current or a well-document historical politican and legal system (for example the U.S. and a particular state, county, and town), and use its constitution, statutes, and court precedents as basic legal precedents, which can then be modified by local courts (in a common-law manner) and other local political authorities. If the U.S. is used as a model, I have suggested some basic changes to make its constitution less subject to the growth of government power. Low exit costs will also greatly help. These kinds of macro-political issues will mostly, however, be well beyond the scope of Seasteading unless or until they reach a time when they are large and mature mobile cities. The first ones will, as with cruise ships today, probably just be based on the "captain is king" model that has long dominated sea law. Friedman has even taken to calling himself "Captain Patri". Perhaps seasteads will revive the old paradigm of political property rights. I wish these projects the best of luck.

Monday, May 19, 2008

Unenumerated sells out

It had to happen -- Unenumerated(tm) has become a Capitalist Tool(tm) -- specifically, it is now part of the Forbes.com blog network. If you are overly annoyed by the ads, would prefer to donate, or have any other general comments about Unenumerated, feel free to leave them here, or you can send them to me at nszabo AT law DOT gwu DOT edu.

Saturday, May 17, 2008

Political bubbles

In response to this Wall Street Journal article, describing a number of scholars developing mathematical models of market bubbles, I posted the following comment at Marginal Revolution which is worth reposting here:
The scholars quoted in the original article sound like they are just engaging in a fancy form of technical analysis, which purports to capture in mathematics the psychology of the crowd, but in almost all cases turns out to be worthless numerology.

The fancy math doesn't explain bubbles any better than [Robert] Schiller's simple driving analogy: there is a big event at an obscure location (let's call it Burning Man, out in the middle of the desert somewhere). People driving to the event are very uncertain of the directions. At a certain intersection, on average 60% of them correctly believe they must turn right and 40% incorrectly believe they must turn left. But they can usually reduce their uncertainty by observing the behavior of others, who are somewhat more likely to be correct than wrong, and altering their [probability estimates] accordingly. Normally this works, but on rare occasions it goes wrong: for example, if the first three cars happen to turn left, the fourth, who had believed with 60% confidence that right was the proper direction, will rationally change his mind and go left. Thus a string of bad luck can make all the cars start going off in the wrong direction, except for those handful of drivers that are strongly confident in their knowledge that one should go right.

Where this analogy goes off the rails as public policy analysis is with the tacit hubris that certain academics from sufficiently elite schools are flying above the whole event in a helicopter and can direct traffic, if only their mathematical analysis is fancy enough. Rather academics and policy makers are in the traffic themselves, generally seeing information biased in ways similar to or even more extreme than the information investors see and act on. In many cases mispriced markets create arbitrage opportunities for truly knowledgeable investors, but analogs to such arbitrage opportunities, i.e. the ability to be rewarded for correcting actual misinformation, are much less prevalent in academic and political policy circles. We should thus expect political policy to be much more prone to biased political fads and herd-following than markets are. Both markets and governments may often take wrong directions, but for politics the inability to correct wrong directions may be endemic. Markets tend to correct themselves, usually in the short run and practically always in the long run, depending on the costs of arbitrage, but there is often no easy way to recognize or correct a political bubble.

Thus, applying the same rational uncertainty assumptions to politics as we do to markets, if we give political decisionmakers the power to "pop" bubbles they think they recognize, they will probably tend to make genuine market bubbles worse, will prevent markets from sending genuine supply and demand signals, and will introduce other extra transaction costs.

Tuesday, May 13, 2008

Ben Bernanke plays John Law

John Law and the Mississippi Bubble are fairly well-known to economic historians, but one wonders whether the supposed economic experts who run the U.S. Federal Reserve remember it.

To briefly summarize (and necessarily oversimply), Law was an economist and gambler put in charge of the French central bank in the early 18th century. The bank issued notes (i.e. paper money) backed primarily reserves of, not gold or silver, nor French sovereign debt, but of stock in the Mississippi Company, which owned huge tracks of recently acquired, but hardly settled, American frontier land. In other words, the currency was backed by speculative real estate ventures. After a few good years, the scheme quickly collapsed in hyperinflation and bankruptcy.

Fast forward to today. The Federal Reserve has traditionally used as reserves, on top of some gold, U.S. federal debt (Treasuries), considered a "risk free" investment (actually they are by market measures of risk generally the lowest risk, but not risk-free, as anyone holding Treasuries during periods of dollar inflation can attest to). Quite recently, however, this has changed:


What has replaced Treasuries in the Fed's hoard? Here's how Randy Waldman puts it:
The difference, about $475B, represents an investment by the central bank in risky assets of the US financial sector.
In other words, the Fed has been replacing the lowest-risk asset, U.S. Treasuries, with assets considered such high risks that trading has often practically halted on them, i.e. the securitized forms of U.S. real estate debt incurred by people who now, we are finding, often cannot or do not pay off their loans. The Federal Reserve is now backing the dollar with securities that have been found to be full of moral hazard.

The Fed does have a tool for eliminating most of this debt problem: inflation. If the Fed can flood the economy with enough dollars, presumably enough of these will reach debtors that they will be able to continue paying their mortgages. By investing in shaky debt, Fed has given itself a huge incentive to further inflate the dollar. It has given itself further incentive to fleece holders of dollar liabilities, including investors in dollar-denominated debt, in order to bail out the real estate market.

We have seen a massive runup in commodity prices during the the same period during which real estate debt has replaced Treasuries in the Fed's portfolio. The dollar has already fallen steeply, and people ranging from retirement funds to second- and third-tie consumers of commodities are hedging against a quite possible further collapse of the dollar. Commodity producers are betting against the dollar by keeping commodities in the ground instead of ramping up production, and food is being stockpiled in every poor country where the currency is linked to the dollar. As I recently wrote:
The dichotomy [most economic commentators have made] between a presumably inefficient "bubble" caused by "speculation" and fundamental (geological and technological) scarcity presents a false choice.

The more likely alternative is that the parallel price rises of practically all commodities (not just oil) are a rational and socially efficient response to the inflation (M3 etc.) of the dollar and to a lesser extent of the euro. The vast increase in "non-commercial" or "speculative" participation in commodity futures reflects a greatly increased use of commodities over the last 5 years for their monetary qualities, just as Carl Menger and others would predict. See Commodity Derivatives: the New Currencies and The "Hoarding" and "Speculation" in Commodities.

Sunday, May 11, 2008

Daydreams in passing

Recently I've been both daydreaming and pondering some of the problems that daydreaming can cause.

I've recently learned that not only do interstellar meteors rudely hit our lovely planet, but some of them may be quite valuable, e.g. black diamond, which leading researchers believe to be the products of supernovae. The Amsterdam diamond sold in 2001 for about $52,000 per gram. The fact that multiple black diamonds have been found on earth suggests that there may be many tonnes of such diamonds flying through the solar system at any given time. By naive extrapolation one tonne of black diamond should be worth $52 billion, but common sense suggests otherwise. If somebody launched a robot to grab a tonne of black diamond out of the darkness of deep space and fling it into the sea, then cut and polished it up for auction, the resulting gem(s) would almost surely fetch only a tiny fraction of that $52 billion. This presents the interesting puzzle: what happens when a collectible, the value of which depends on its stable scarcity, (and thus, its shape of its demand curve depends in part on the shape of its supply curve), suddenly is discovered to be common? Its price might fall far faster than would be expected for a normal commodity demanded solely for its consumption. This suggests, too, that the recent rise in the use of commodities for their monetary properties may in some cases be quite fragile. Where new cheap sources or substitutions are discovered for a commodity, the price of that commodity might fall much farther and faster than if consumption alone shaped the demand curve. This may be a good argument for the gold bugs, if such a breakthrough is less likely for precious metals like gold than for other commodities. I find it a good argument for diversification across a basket or index of commodities. Either of these strategies is still vulnerable to a a return to good fiat currency policy by the U.S. Federal Reserve or the European Central Bank.

Speaking of daydreaming about space, Mike Thomas well describes the utter waste NASA has made, and is still trying to make, out of our tax money and our daydreams. That NASA has talked many space fans into believing that government can successfuly plan for and design infrastructure for hypothetical future business exceeds in idiocy even the old state socialism, which showed time and again (with over a hundred million starved) that central agencies couldn't plan satisfactorily for even present industrial needs.

And now for a nice exercise in pure daydreaming: SETI, the Search for Extraterrestrial Intelligence. The Drake Equation makes it all sound very scientific, but plausible inputs into the Drake Equation can make its ouptut vary by nearly twenty orders of magnitude. At one extreme there may be no civilizations in the visible universe except us. At the other extreme many SETI people believe that each galaxy may be full of millions of rather compressed and cryptic civilizations. There are plenty of people who find one extreme quite plausible and the other quite implausible, for each extreme, and plenty of plausible arguments for each side, but in fact we just don't know. SETI is an obvious example of an error that is far too common, if less obviously so, in many other areas of science: too many people who style themselves as scientists present highly uncertain opinions, based on obscure or questionable assumptions, as if they were accurate facts or settled theories. The precision and confidence of their language often far exceeds their accuracy. Modern science is so specialized that even the vast majority of fellow scientists often don't have the time to dig in to unearth the hidden assumptions behind their fellows' claims. They like us come to accept opinions, possibly of a highly uncertain nature, as facts based on the authority of the scientists.

Mistaking precision for accuracy is also one of the big problems with with attempting to predict the future needs of commerce, as NASA has purported to do. As if exagerated claims to accuracy and the hiding of assumptions weren't bad enough, due to the dominance of one kind of funding, namely government funding, most of the scientists in some fields share common biases, especially political biases to justify expanded government budgets. Authority increasingly takes the form of political power, funding increasingly requires political power, and political power, rather than facts, has been increasingly the source of "scientific consensus." Here is more on the the trouble with modern science.