Trying to beat the protocol can get you in trouble:
Saturday, January 31, 2009


Confidential auditing
I once described how confidential auditing was possible and beneficial:
But my description was only a proof-of-concept sketch that one could go all the way from preparing to transact to transaction log to finished audits while maintaining both integrity and privacy, with neither depending on large amounts of trust in the auditors. Recently Shen et. al. came up with a detailed design of such a confidential auditing scheme in the context of gathering statistics from the logs of distributed computations:
The auditing function is a vast and indispensable part of the modern economy. Auditing controls allow, among other things, employers to delegate resources and authority to employees, franchisors to delegate to franchisees, stockholders to delegate to management, advertisers to count eybeballs, marketers to gather more reliable data on customers, and make possible a wide variety of other such relationships. Auditing controls might fairly be called the security protocols of capitalism...[However,] auditing is in deep conflict with efforts towards greater privacy. Auditors have an ethic of recording, investigating, and reporting as much as possible, and often see privacy efforts as attempts to prevent auditing and potentially cover up fraud...[But confidential auditing is possible because] we can achieve auditing logs unforgeable after commitment via secure timestamps. We can then achieve to a great extent unforgeability prior to commitment, with segregation of duties via multiparty integrity constraints. We then audit these commitments via multiparty private computations.In an article about multiparty secure (i.e. private) computations I described this process as follows:
Performance phase analysis with multiparty secure computer theory would seem to apply only to those contracts which can be performed inside the virtual computer. But the use of post-unforgeable auditing logs, combined with running auditing protocols inside the shared virtual computer, allows a wide variety of performances outside the virtual computer to at least be observed and verified by selected arbitrators, albeit not proactively self-enforced.In this I had been inspired by Eric Hughes' idea of encrypted open books. My sketch is more general insofar as it addresses pre-transaction forging (with separation of duties), post-transaction forging (with secure timestamping), and the auditing protocol itself (with multiparty private computation running off the logs themselves rather than Hughes' specialized protocol running off already prepared books).
The participants in this mutually confidential auditing protocol can verify that the books match the details of transactions stored in a previously committed transaction log, and that the numbers add up correctly. The participants can compute summary statistics on their confidentially shared transaction logs, including cross-checking of the logs against counterparties to a transaction, without revealing those logs. They only learn what can be inferred from the statistics; [they] can't see the details of the transactions
But my description was only a proof-of-concept sketch that one could go all the way from preparing to transact to transaction log to finished audits while maintaining both integrity and privacy, with neither depending on large amounts of trust in the auditors. Recently Shen et. al. came up with a detailed design of such a confidential auditing scheme in the context of gathering statistics from the logs of distributed computations:
...no single TTP [trusted third party] node can have the full knowledge of the logs, and thus no single node can misuse the log information without being detected. On the basis of a relaxed form of secure distributed computing paragidms, one can implement confidential auditing service so that the auditor can retrieve certain aggregated system information e.g., the number of transactions, the total volume, the event traces, etc., without having to access the full log data...To prevent an unsupervised TTP from manipulating the system, we design query processing schemes that require TTP nodes work together, using the multiparty private computation, to perform any useful auditing functions.
Secure timestamping and confidential auditing
Another interesting protocol is cryptographic timestamping. The purpose is to prove that a particular piece of content (i.e. some array of bits) existed at a particular period of time. The basic idea goes back to the anagram publication technique that Robert Hooke, Galileo, and some other early scientists used to prove that they discovered certain things long before they published them. When Hooke, for example, discovered his law of elasticity, he published the gobbledygook letters "ceiiinosssttuv." Later, when he published his law of elasticity, he published "ut tensio sic vis" (as the extension, so with the force). The earlier published anagram proved that he had discovered this law long before he published it.
The modern protocol uses cryptographic hash functions instead of anagrams. Any set of bits (digital content, a network event, whatever) is passed through the hash function, turning into into a unique random-looking string of bits. Those bits are then published to multiple timestamp servers on the Internet. The timestamp servers create a chain of hashes. Using the chain of published hashes, it is easy to later prove that (1) the hash was published before one event and after another event, thus proving the time of publication, and (2) that the hash uniquely corresponds to a particular content.
Note that the content of the file does not need to be published until proof is needed. Thus, for example, one could digitally timestamp a secret digital inventor's notebook in order to prove later that the invention existed at that time. (Might be quite useful under the American first-to-invent system).
Indeed, using multiparty secure computation or the related protocols called zero-knowledge proofs, one can even make a later proof without publishing the content. For example, if Bob received a secret encrypted e-mail message from Alice, Alice and Bob could prove to the world that Alice sent a message at 18:42:39 and Bob received it at 18:43:05 without revealing the actual contents of the message. In a confidential audit of Alice's books based on securely timestamped transactions between Alice and Bob and Alice and Charles, performed using secure multiparty computation, Alice can prove to the auditor that her books balance based on real transactions with Bob and Charles, without revealing in unencrypted form to the auditor either the transactions or the books. Such is the magical reality of cryptography!
Here are some links to papers and other references on secure timestamping.
Saturday, December 27, 2008
Bit gold markets
The basic idea of bit gold is for "bit gold miners" to set their computers to solving computationally intensive mathematical puzzles, then to publish the solutions to these puzzles in secure public registries, giving them unique title to these provably scarce and securely timestamped bits. These titles to timestamped bits will be more secure and provably scarce than precious metals, collectibles, and any other objects that have ever been used as money. In a description of bit gold, which was mostly an overview of the technology, I wrote about how, because the algorithms and architectures for solving computationally intensive mathematical puzzles to create bit gold will often be dramatically improved, the bits (the puzzle solutions) from one period (anywhere from seconds to weeks, let's say a week) to the next are not fungible. But fungible units can be created from non-fungible ones:
It's a bit indirect, but computers can easily handle these logistics. Leaving aside the gold metaphor for a minute, one can think of these bit strings as digital rare postage stamps. Each stamp might trade for a different price, but one can sort stamps into pools so that the prices of stamps in each pool add up to the same total price. Then divide each pool into tranches to create your standard currency denominations.
The rare stamp metaphor is, however, in other ways very misleading. Unlike stamps, but like gold, there are no ongoing changes in subjective valuations between bit strings to worry about, but instead the demand for bit gold is purely for its monetary functions, and thus purely based on how scarce the supply of puzzles solved during a given time period was and is. As a result, pooling and tranching will work far better for bit gold than it does for actual rare postage stamps.
This deserves more elaboration. It seems to be a common objection to bit gold that the mere difference in the price of a bit from one time period to the next produced by technology improvements introduce intractible subjective valuations, making the matter of comparing one week to the next subject to too much uncertainty and transaction costs, as occurs with many collectibles. Just as pooling and tranching rare postage stamps would be a somewhat risky affair as subjective valuations of the underlying stamps change, so too this is supposed for bit gold.
The problem that would occur if we tried to turn most collectibles into a standard currency by pooling and tranching is that, besides a subjective aesthetic component in the demand curve that doesn't come into play with computer bits, their scarcity is uncertain. Art can turn out to be forged, rare stamps thought to be lost or to have never existed might be found, and so on. The supply curve, in other words, can be highly uncertain and in danger of elasticity. Since the supply and demand curves of different pools can change differently over time, the relative values of pools would diverge from their initial values, so that trying to use tranches as standard denominations of a currency would create arbitrage opportunities.
By sharp contrast bit gold will be entirely public: no one gains secure title to any puzzle solutions until they are published. Thus, the exact amount and kind of puzzle solutions during a given period are well known, and perfectly define the supply curve relative to future weeks for all time thereafter.
There will be, in other words, a perfectly objective, measurable, and inelastic supply curve, completely derivable from the relative scarcity of bits (puzzle solutions) on the week (or the day, or the hour, or the minute, if necessary) of their publication. Arbitrage to set the different prices of different weeks (or minutes) can be computerized on this basis. The demand curve, the demand for puzzle solutions for the monetary functions they can perform as a store of value and medium of exchange, will be based on recognition of the superiority of bit gold as a form of money that is more secure and has a far less elastic supply curve than traditional commodities such as precious metals. Since there are no aesthetic differences, the demand curve will be the same function of scarcity for all weeks (or minutes), so it won't affect the simple scheme of automated arbitrage between epochs with different supply curves. The supply and demand curves of different pools will change in the same way over time, and the relative values of pools will not diverge from their initial relative values. Using tranches as standard denominations for a currency does not create arbitrage opportunities.
For most of history collectibles were used for as stores of value and media of exchange; aesthetics played an important role. But before we can separate out the roles of scarcity and aesthetics, we must ask why humans evolved such aesthetic values. The aesthetic instincts, for example the instinct to collect shiny things, evolved just because in the evolutionary environment they approximated an instinct to collect scarce things, and to distinguish hard-to-find from easy-to-find things, i.e. an instinct to recognize and collect objects that can best perform monetary functions, as I describe here, in the "Evolution..." section early in the paper, and the "Attributes of Collectibles" section late in the paper.
As a proximate matter, the contribution to the demand curve from demand for monetary functions (store of value or medium of exchange or both) and the contribution from aesthetic considerations are completely separable. One can demand a commodity for its aesthetic value, or for its value as money, or for both, or for neither. Thus a check for a million dollars might have a design that is utterly philistine, yet the check is still worth a million dollars.
The value of gold today is almost entirely based on its monetary value rather than mere aesthetic value. There are plenty of metals that are as shiny and smooth as gold, but people don't demand them as a store of value or medium of exchange because they are common. There are plenty of rocks that look as good as diamonds, but "diamonds are a girl's best friend" because they are hard to obtain and thus hold their value. Value comes to attach to the unique aesthetic features of gold or diamonds because these features signal scarcity. The value of precious metals or gems as stores of value, media of exchange, or even as cultural icons does not come from these aesthetic features, it is only signalled by them. It is their secure scarcity, not their aesthetic features, that allows them to be more securely used as a store of value and thus gives them a monetary value, and often a corresponding emotional and cultural value, far above the often trivial value they would have if they had the same aesthetics but were common.
There will be a problem defining futures contracts for yet-to-be produced bit gold: how much it might cost to solve a given puzzle a year later, or even a month, will be a very uncertain matter. But the pools that define currencies will be based on spot prices for already produced bit gold, not on futures.
[These comments edit and add to comments of mine under previous blog post(s)]
bit gold will not be fungible based on a simple function of, for example, the length of the string. Instead, to create fungible units dealers will have to combine different-valued pieces of bit gold into larger units of approximately equal value. This is analogous to what many commodity dealers do today [pooling commodities with a wide variety of qualities into a handful of standard grades] to make commodity markets possible.Bit strings (puzzle problem/solution pairs) are securely timestamped by their time of publication. More recent solutions that have been produced in greater quantities will be discounted by markets. To create fungible units dealers will bundle strings of different value into pools of a standard value (i.e. collect strings into a pool so that the sum of the market values of the strings in the pool add up to the standard value).
It's a bit indirect, but computers can easily handle these logistics. Leaving aside the gold metaphor for a minute, one can think of these bit strings as digital rare postage stamps. Each stamp might trade for a different price, but one can sort stamps into pools so that the prices of stamps in each pool add up to the same total price. Then divide each pool into tranches to create your standard currency denominations.
The rare stamp metaphor is, however, in other ways very misleading. Unlike stamps, but like gold, there are no ongoing changes in subjective valuations between bit strings to worry about, but instead the demand for bit gold is purely for its monetary functions, and thus purely based on how scarce the supply of puzzles solved during a given time period was and is. As a result, pooling and tranching will work far better for bit gold than it does for actual rare postage stamps.
This deserves more elaboration. It seems to be a common objection to bit gold that the mere difference in the price of a bit from one time period to the next produced by technology improvements introduce intractible subjective valuations, making the matter of comparing one week to the next subject to too much uncertainty and transaction costs, as occurs with many collectibles. Just as pooling and tranching rare postage stamps would be a somewhat risky affair as subjective valuations of the underlying stamps change, so too this is supposed for bit gold.
The problem that would occur if we tried to turn most collectibles into a standard currency by pooling and tranching is that, besides a subjective aesthetic component in the demand curve that doesn't come into play with computer bits, their scarcity is uncertain. Art can turn out to be forged, rare stamps thought to be lost or to have never existed might be found, and so on. The supply curve, in other words, can be highly uncertain and in danger of elasticity. Since the supply and demand curves of different pools can change differently over time, the relative values of pools would diverge from their initial values, so that trying to use tranches as standard denominations of a currency would create arbitrage opportunities.
By sharp contrast bit gold will be entirely public: no one gains secure title to any puzzle solutions until they are published. Thus, the exact amount and kind of puzzle solutions during a given period are well known, and perfectly define the supply curve relative to future weeks for all time thereafter.
There will be, in other words, a perfectly objective, measurable, and inelastic supply curve, completely derivable from the relative scarcity of bits (puzzle solutions) on the week (or the day, or the hour, or the minute, if necessary) of their publication. Arbitrage to set the different prices of different weeks (or minutes) can be computerized on this basis. The demand curve, the demand for puzzle solutions for the monetary functions they can perform as a store of value and medium of exchange, will be based on recognition of the superiority of bit gold as a form of money that is more secure and has a far less elastic supply curve than traditional commodities such as precious metals. Since there are no aesthetic differences, the demand curve will be the same function of scarcity for all weeks (or minutes), so it won't affect the simple scheme of automated arbitrage between epochs with different supply curves. The supply and demand curves of different pools will change in the same way over time, and the relative values of pools will not diverge from their initial relative values. Using tranches as standard denominations for a currency does not create arbitrage opportunities.
For most of history collectibles were used for as stores of value and media of exchange; aesthetics played an important role. But before we can separate out the roles of scarcity and aesthetics, we must ask why humans evolved such aesthetic values. The aesthetic instincts, for example the instinct to collect shiny things, evolved just because in the evolutionary environment they approximated an instinct to collect scarce things, and to distinguish hard-to-find from easy-to-find things, i.e. an instinct to recognize and collect objects that can best perform monetary functions, as I describe here, in the "Evolution..." section early in the paper, and the "Attributes of Collectibles" section late in the paper.
As a proximate matter, the contribution to the demand curve from demand for monetary functions (store of value or medium of exchange or both) and the contribution from aesthetic considerations are completely separable. One can demand a commodity for its aesthetic value, or for its value as money, or for both, or for neither. Thus a check for a million dollars might have a design that is utterly philistine, yet the check is still worth a million dollars.
The value of gold today is almost entirely based on its monetary value rather than mere aesthetic value. There are plenty of metals that are as shiny and smooth as gold, but people don't demand them as a store of value or medium of exchange because they are common. There are plenty of rocks that look as good as diamonds, but "diamonds are a girl's best friend" because they are hard to obtain and thus hold their value. Value comes to attach to the unique aesthetic features of gold or diamonds because these features signal scarcity. The value of precious metals or gems as stores of value, media of exchange, or even as cultural icons does not come from these aesthetic features, it is only signalled by them. It is their secure scarcity, not their aesthetic features, that allows them to be more securely used as a store of value and thus gives them a monetary value, and often a corresponding emotional and cultural value, far above the often trivial value they would have if they had the same aesthetics but were common.
There will be a problem defining futures contracts for yet-to-be produced bit gold: how much it might cost to solve a given puzzle a year later, or even a month, will be a very uncertain matter. But the pools that define currencies will be based on spot prices for already produced bit gold, not on futures.
[These comments edit and add to comments of mine under previous blog post(s)]
Bit gold
A long time ago I hit upon the idea of bit gold. The problem, in a nutshell, is that our money currently depends on trust in a third party for its value. As many inflationary and hyperinflationary episodes during the 20th century demonstrated, this is not an ideal state of affairs. Similarly, private bank note issue, while it had various advantages as well as disadvantages, similarly depended on a trusted third party.
Precious metals and collectibles have an unforgeable scarcity due to the costliness of their creation. This once provided money the value of which was largely independent of any trusted third party. Precious metals have problems, however. It's too costly to assay metals repeatedly for common transactions. Thus a trusted third party (usually associated with a tax collector who accepted the coins as payment) was invoked to stamp a standard amount of the metal into a coin. Transporting large values of metal can be a rather insecure affair, as the British found when transporting gold across a U-boat infested Atlantic to Canada during World War I to support their gold standard. What's worse, you can't pay online with metal.
Thus, it would be very nice if there were a protocol whereby unforgeably costly bits could be created online with minimal dependence on trusted third parties, and then securely stored, transferred, and assayed with similar minimal trust. Bit gold.
My proposal for bit gold is based on computing a string of bits from a string of challenge bits, using functions called variously "client puzzle function," "proof of work function," or "secure benchmark function.". The resulting string of bits is the proof of work. Where a one-way function is prohibitively difficult to compute backwards, a secure benchmark function ideally comes with a specific cost, measured in compute cycles, to compute backwards.
Here are the main steps of the bit gold system that I envision:
(1) A public string of bits, the "challenge string," is created (see step 5).
(2) Alice on her computer generates the proof of work string from the challenge bits using a benchmark function.
(3) The proof of work is securely timestamped. This should work in a distributed fashion, with several different timestamp services so that no particular timestamp service need be substantially relied on.
(4) Alice adds the challenge string and the timestamped proof of work string to a distributed property title registryfor bit gold. Here, too, no single server is substantially relied on to properly operate the registry.
(5) The last-created string of bit gold provides the challenge bits for the next-created string.
(6) To verify that Alice is the owner of a particular string of bit gold, Bob checks the unforgeable chain of title in the bit gold title registry.
(7) To assay the value of a string of bit gold, Bob checks and verifies the challenge bits, the proof of work string, and the timestamp.
Note that Alice's control over her bit gold does not depend on her sole possession of the bits, but rather on her lead position in the unforgeable chain of title (chain of digital signatures) in the title registry.
All of this can be automated by software. The main limits to the security of the scheme are how well trust can be distributed in steps (3) and (4), and the problem of machine architecture which will be discussed below.
Hal Finney has implemented a variant of bit gold called RPOW (Reusable Proofs of Work). This relies on publishing the computer code for the "mint," which runs on a remote tamper-evident computer. The purchaser of of bit gold can then use remote attestation, which Finney calls the transparent server technique, to verify that a particular number of cycles were actually performed.
The main problem with all these schemes is that proof of work schemes depend on computer architecture, not just an abstract mathematics based on an abstract "compute cycle." (I wrote about this obscurely several years ago.) Thus, it might be possible to be a very low cost producer (by several orders of magnitude) and swamp the market with bit gold. However, since bit gold is timestamped, the time created as well as the mathematical difficulty of the work can be automatically proven. From this, it can usually be inferred what the cost of producing during that time period was.
Unlike fungible atoms of gold, but as with collector's items, a large supply during a given time period will drive down the value of those particular items. In this respect "bit gold" acts more like collector's items than like gold. However, the match between this ex post market and the auction determining the initial value might create a very substantial profit for the "bit gold miner" who invents and deploys an optimized computer architecture.
Thus, bit gold will not be fungible based on a simple function of, for example, the length of the string. Instead, to create fungible units dealers will have to combine different-valued pieces of bit gold into larger units of approximately equal value. This is analogous to what many commodity dealers do today to make commodity markets possible. Trust is still distributed because the estimated values of such bundles can be independently verified by many other parties in a largely or entirely automated fashion.
In summary, all money mankind has ever used has been insecure in one way or another. This insecurity has been manifested in a wide variety of ways, from counterfeiting to theft, but the most pernicious of which has probably been inflation. Bit gold may provide us with a money of unprecedented security from these dangers. The potential for initially hidden supply gluts due to hidden innovations in machine architecture is a potential flaw in bit gold, or at least an imperfection which the initial auctions and ex post exchanges of bit gold will have to address.
Saturday, October 11, 2008
Origins of the joint-stock corporation
The modern joint-stock corporation has many sources in medieval Europe. First among these was corporate law itself. Although the era is commonly referred to as "feudalism," for the hierarchy of individually owned "fiefs" of land and control of serfs as fixtures of that land, large amounts of wealth in Europe were actually controlled by corporate entities. Chief among these were church lands, the corporate entities being dioceses, religious orders and the Roman Church itself. These entities controlled a substantial fraction of the land in Western Europe. Furthermore cities (with varying degrees of political independence), merchant guilds, craft guilds, and many charitable entities (such as hospitals) were legal "corporations," i.e. artificial and perpetual legal persons under law. Some basic issues in corporate law (for example, when are officers individually liable for acts of the corporation, and when the corporation is liable for acts of its agents) had already been solved in canon law and urban law long before the joint-stock corporation.
Another source of the joint-stock corporation was the tradition of dividing ownership over tangible things into "shares." For example, it was common in Italian maritime states fund the construction and operation of ships by dividing them into a certain number of shares (24 and 64 were common divisions). Share owners were responsible for funding voyages (not including cargo, which was typically paid for by trading partnerships called commenda) as well as the initial construction capital, and divided up the profits (fees paid by the merchants less costs). This tradition faded away in Venice when that republic's government took over ship ownership, but thrived across the Italian penninsula in Genoa. Ship shares became embedded into maritime law all over Europe and even survived the British Empire (today in Canada when you register a boat the government still registers 64 shares in it for its owner). The only organization controlled by the shareholders, however, was the captain and crew of the ship.
The medieval organizations that most resembled later joint-stock corporations were the Genovese maone. These bore some strong resemblances to the publicani tax farming corporations of the Roman Republican era, although it is not clear how they could have survived the intervening Late Empire and Dark Ages other than as very obscure (and perhaps now lost) written descriptions. In form and function maone also bore strong resemblances to some early joint-stock companies such as the Bank of Amsterdam, Bank of England, and the Dutch and English East India Companies.
The Italian cities often sold off their tax receivables to wealthy merchants at a discount as a way to borrow funds. (Discounting was one of the many ways late medieval financiers avoided the rather lax and narrow usury restrictions). The debts were divided into equal shares called loca or partes. Legally, these shares were personal property (chattels) and could be freely traded.
Technically, no organization was created when the city sold its tax receivables to merchants. However, to effectively collect the taxes, the holders of loca formed an organization called a maona or societas comperarum. This organization would then subcontract to tax farmers to collect the taxes. By the fourteenth century, Genovese maone also engaged in military conquest and colonization. These were, quite literally, corporate raiders.
Normally, maone were temporary, but some of them ended up lasting for a long time. In 1346 the Maona di Chio e di Focea (a company for managing the taxes of Chios and Focea) was formed. This organization's members obtained from Genoa the exclusive right to collect taxes from Chios (an Aegean island) and Phocaea (a port on the Anatolian coast). But first the company would have to conquer them! Although technically a temporary organization, it lasted until 1566.
Rather than going to buy receivables from Genoa, subscriptions to the di Chio e di Focea's loca shares (still legally debt, but to be paid out in dividends as taxes and trading revenues were collected) went to fund 29 galleys to conquer Chios and Phocaea. The Genovese Republic, for a fee, granted the organization exclusive rights to collect taxes from the conquered territories as well as special trading privileges. The conquests, taxes, and trading were at least partially successful, and by the 16th century more than 600 persons owned loca of the maona. This function and some of this structure would later be emulated by the Dutch and English India Companies, but with a basic legal difference -- "shares" in these later joint-stock companies would constitute ownership (like ship shares) not debt as with the maona.
The most famous Genovese maona was the Officium procuratorum San Giorgio, later the Banco di San Giorgio. Founded in 1407, this bank (and a later Genovese bank along the same lines, the Bank of Genoa) would be the inspiration for later central banks such as the Bank of Amsterdam and the Bank of England. Banco di San Giorgio came to administer most of the Genovese Republic's debts. Dividends were paid out of tax collections (less directly than with earlier maona, but still more directly than the later Bank of England). The maona business was becoming more monopolistic, as it had become in Venice and would become with later central banks.
At the same time, however, the ship share system spread to northern Europe and branched out beyond ships. In Italy and Germany by the 16th century a wide variety of mines were divied up into ownership shares. During the Reformation, a pious follower of Martin Luther gave him some kuxen, shares in a mine in Saxony. Luther complained that he did not know what to do with them. (Indeed, since as with ship shares the mine managers could call on investors to pay up more capital, ownership was not for the financially naive).
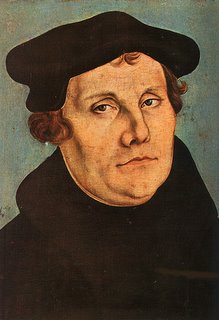
Martin Luther
Ship shares and mine shares like these were issued in small numbers (usually between 24 and 640) and thus were not typically traded on exchanges. The number of employees was also small, usually no more than a few dozen. Kuxen were reportedly sometimes traded at the Leipzig fairs. Indeed, illiquidity was the rule in the first century of English joint-stock companies. It was not until the Vereenigde Oostindische Compagnie (the Dutch East India Company, founded out of a merger of smaller colonial companies in 1602) that volume existed to trade company shares on exhanges (which up to that time traded state and municipal bonds and commodities).
Interestingly, the first joint-stock companies chartered by the English Crown (starting in 1553) were companies involved in trading (the Muscovy and Levant companies), mining (the Royal Mines and the Mineral and Battery), and trading combined with conquest (the India Companies, the Virginia and Plymouth companies, etc.) The two mining companies borrowed not only shares but managers and engineers (presumably along with their techniques) from Germany. The Genovese for their part would have felt at home with the trading and conquest companies.
References include:
Harold Berman, Law and Revolution.
Guido Ferrarini, "Origins of Limited Liability Companies and Company Law Modernisation in Italy: A Historical Outline", Centro di Diritto e Finanza WP 5-2002.
Meir Kohn, "The Capital Market Before 1600", working paper 99-06, February 1999.
Another source of the joint-stock corporation was the tradition of dividing ownership over tangible things into "shares." For example, it was common in Italian maritime states fund the construction and operation of ships by dividing them into a certain number of shares (24 and 64 were common divisions). Share owners were responsible for funding voyages (not including cargo, which was typically paid for by trading partnerships called commenda) as well as the initial construction capital, and divided up the profits (fees paid by the merchants less costs). This tradition faded away in Venice when that republic's government took over ship ownership, but thrived across the Italian penninsula in Genoa. Ship shares became embedded into maritime law all over Europe and even survived the British Empire (today in Canada when you register a boat the government still registers 64 shares in it for its owner). The only organization controlled by the shareholders, however, was the captain and crew of the ship.
The medieval organizations that most resembled later joint-stock corporations were the Genovese maone. These bore some strong resemblances to the publicani tax farming corporations of the Roman Republican era, although it is not clear how they could have survived the intervening Late Empire and Dark Ages other than as very obscure (and perhaps now lost) written descriptions. In form and function maone also bore strong resemblances to some early joint-stock companies such as the Bank of Amsterdam, Bank of England, and the Dutch and English East India Companies.
The Italian cities often sold off their tax receivables to wealthy merchants at a discount as a way to borrow funds. (Discounting was one of the many ways late medieval financiers avoided the rather lax and narrow usury restrictions). The debts were divided into equal shares called loca or partes. Legally, these shares were personal property (chattels) and could be freely traded.
Technically, no organization was created when the city sold its tax receivables to merchants. However, to effectively collect the taxes, the holders of loca formed an organization called a maona or societas comperarum. This organization would then subcontract to tax farmers to collect the taxes. By the fourteenth century, Genovese maone also engaged in military conquest and colonization. These were, quite literally, corporate raiders.
Normally, maone were temporary, but some of them ended up lasting for a long time. In 1346 the Maona di Chio e di Focea (a company for managing the taxes of Chios and Focea) was formed. This organization's members obtained from Genoa the exclusive right to collect taxes from Chios (an Aegean island) and Phocaea (a port on the Anatolian coast). But first the company would have to conquer them! Although technically a temporary organization, it lasted until 1566.
Rather than going to buy receivables from Genoa, subscriptions to the di Chio e di Focea's loca shares (still legally debt, but to be paid out in dividends as taxes and trading revenues were collected) went to fund 29 galleys to conquer Chios and Phocaea. The Genovese Republic, for a fee, granted the organization exclusive rights to collect taxes from the conquered territories as well as special trading privileges. The conquests, taxes, and trading were at least partially successful, and by the 16th century more than 600 persons owned loca of the maona. This function and some of this structure would later be emulated by the Dutch and English India Companies, but with a basic legal difference -- "shares" in these later joint-stock companies would constitute ownership (like ship shares) not debt as with the maona.
The most famous Genovese maona was the Officium procuratorum San Giorgio, later the Banco di San Giorgio. Founded in 1407, this bank (and a later Genovese bank along the same lines, the Bank of Genoa) would be the inspiration for later central banks such as the Bank of Amsterdam and the Bank of England. Banco di San Giorgio came to administer most of the Genovese Republic's debts. Dividends were paid out of tax collections (less directly than with earlier maona, but still more directly than the later Bank of England). The maona business was becoming more monopolistic, as it had become in Venice and would become with later central banks.
At the same time, however, the ship share system spread to northern Europe and branched out beyond ships. In Italy and Germany by the 16th century a wide variety of mines were divied up into ownership shares. During the Reformation, a pious follower of Martin Luther gave him some kuxen, shares in a mine in Saxony. Luther complained that he did not know what to do with them. (Indeed, since as with ship shares the mine managers could call on investors to pay up more capital, ownership was not for the financially naive).

Martin Luther
Ship shares and mine shares like these were issued in small numbers (usually between 24 and 640) and thus were not typically traded on exchanges. The number of employees was also small, usually no more than a few dozen. Kuxen were reportedly sometimes traded at the Leipzig fairs. Indeed, illiquidity was the rule in the first century of English joint-stock companies. It was not until the Vereenigde Oostindische Compagnie (the Dutch East India Company, founded out of a merger of smaller colonial companies in 1602) that volume existed to trade company shares on exhanges (which up to that time traded state and municipal bonds and commodities).
Interestingly, the first joint-stock companies chartered by the English Crown (starting in 1553) were companies involved in trading (the Muscovy and Levant companies), mining (the Royal Mines and the Mineral and Battery), and trading combined with conquest (the India Companies, the Virginia and Plymouth companies, etc.) The two mining companies borrowed not only shares but managers and engineers (presumably along with their techniques) from Germany. The Genovese for their part would have felt at home with the trading and conquest companies.
References include:
Harold Berman, Law and Revolution.
Guido Ferrarini, "Origins of Limited Liability Companies and Company Law Modernisation in Italy: A Historical Outline", Centro di Diritto e Finanza WP 5-2002.
Meir Kohn, "The Capital Market Before 1600", working paper 99-06, February 1999.
Emergency economics

For those of you who didn't catch me on econ-law a few months ago [2005] during the hurricanes, here is an expanded version of what I posted there:
Here are some alternative ways of rationing in an emergency. At least some of these have been written about by Yoram Barzel. We have witnessed all of them during hurricane Katrina [and also this summer (2008) during Ivan]:
(1) market prices ("price gouging")It's not clear that, even with perfect knowledge, with or without an emrgency, centrally planned rationing could operate without using one of the other methods of rationing. In any case, our very poor knowledge about each others' needs is sufficient to ensure that, short of a perfect price system, we can't get what we want without waiting in line, and sometimes we just can't get what we want (or even, the Rolling Stones notwithstanding, what we need). The worse the price system -- in other words, the higher the transaction costs -- the more we wait in line or do without, as East Germany once demonstrated (cf. West Germany) and as North Korea continues to demonstrate. Luckily for those of us in largely market price based economies, we need only wait in line when trying to do business with the government, call a toll-free service line, go to a hot movie on opening night, or during an emergency -- i.e. in the remaining situations where prices don't operate very well or at all, due to transaction costs imposed by law or otherwise.
(2) waiting in line
(3) centrally planned rationing
(4) don't ration: just let the resource run out
Mises and Hayek long ago demonstrated the weakness of centrally planned economies such as the old Soviet Union (or today's North Korea) -- the lack of knowledge the government has about peoples' needs and desires. Similarly, lack of the requisite detailed rknowledge of the needs of others, especially at specific times of crisis when they need our help most, is a huge problem even if we were perfectly charitable. Not even the local governments exhibited much knowledge of the needs of their neighbors, especially in New Orleans. Much less did the state or Feds (FEMA being only the most glaring example) exhibit even a tiny fraction of the knowledge that would be required for an optimal outcome. This is not the fault of the people in the government agencies to not act as knowlegeably as they are capable of acting, but rather the fault is in their implied promises and our expectations. For example, TV commentators, watching pictures of some Coast Guard helicopters, seem to have come to expect that government agencies will swoop down from the sky and rescue everybody and take on other attributes of God. Such as, for example, being able to knowledgeably evacuate people and distribute other scarce goods and services in a disaster.
Per Mises and Hayek, even if the Soviet Union had been run by an perfectly beneficient dictator, people would have, short of a matching omniscience of said dictator (and of enough of his underlings to receive and act on the knowledge) still have waited in bread lines. When price controls hit gasoline in the United States in the 1970s, people similarly waited in gas lines.
In emergencies rationing becomes extreme: people wait in long lines, pay "extortionate" prices, or, even worse, do without. We are thrown into economically unfamiliar territory and transaction costs balloon. Goods will always be rationed in one or more of the above four ways, and in an emergency the rationing can be quite severe. Our charitable spirit can temporarily overcome self-interest, but it can't overcome the knowledge problem or the scarcity of goods.
Given that waiting in line, or doing without, are very painful (even sometimes deadly) alternatives, and that allowing the charge of very high prices can largely prevent use of these extreme and wasteful forms of rationing, why do we have price gouging laws?
Can price gouging laws be explained as follows? In a zero transaction cost world, consumers would successfully negotiate with retailers for an insurance policy that caps prices in case of emergency. This may be, for example, because retailers are better able to bear the risk of emergency supply shortages than consumers are, or because consumers don't want to bear the risk of having to have an unusually large amount of money at hand during an emergency. (Katrina may be a good example of this -- it reportedly struck just before many paychecks were due, leaving many people who live from paycheck to paycheck without funds). However, the transaction costs for negotiating with consumers for such contracts are too high. Therefore, the default retail sales contract should include such insurance. Price gouging laws are a convenient way to do this. More generally, if it weren't such a bother almost all of us would like to purchase insurance against volatile prices in order to make our budgets more predictable.
Whether and when wholesale contracts include such price caps provisions would provide interesting evidence in favor of or against this hypothesis, and under what conditions it would have been rational to for consumers and retailers to have made such a contract.

As we have seen, there is a strong economic argument against price gouging laws. Consistent application of market pricing during an emergency would minimize the other inefficient, and occasionally deadly, rationing methods above, especially (4)actually running out of emergency supplies. Consumers could be confident that supplies will not run out, so stocking up on excess supplies based on fear of imminently running out of the supply (such as we've seen consumers do in some areas recently with gasoline) would be minimized. Given modern technology, perhaps we should work on improving the availability of credit and liquidity in emergencies via always-up wireless devices and immediately payable liquidity insurance policies instead of price gouging laws.
Furthermore, the promise of very high prices might motivate retailers to fly in special deliveries of emergency supplies at otherwise prohibitive transportation rates. On can even imagine for-profit organizations doing many of the tasks that the National Guard, Red Cross, and similar organizations are doing now. Of course, the moral indignation would be enormous. People, at least in political discussion, tend to be extremely averse to "windfall profits" and seem to have a strong psychological preference for an implicit insurance policy that puts a price cap during emergencies on retail contracts.
Monday, September 22, 2008
Patent goo: self-replicating Paxil
In his novel Cat’s Cradle, science fiction writer Kurt Vonnegut postulated “Ice-9.” Ice-9 was a form of water that was frozen at room temperature and catalyzed any normal water it came in contact with into more crystals of Ice-9. Once released into the environment, it froze all water, including us. Eric Drexler in the 1980s raised the specter of nano-robots that made copies of themselves and ate everything in their path: "gray goo." A wide variety of similar hypothetical disasters have since been given referred to as some sort of "goo."
Self-replicating chemicals are not merely hypothetical: since Cat's Cradle, scientists have discovered some real-world example of crystals that seed the environment, converting other forms (polymorphs) of the crystal into their own. The population of the original polymorph diminishes as it is converted into the new form: it is a “disappearing polymorph.” In 1996 Abbott Labs began manufacturing the new anti-AIDS drug ritonavir. In 1998 a more stable polymorph appeared in the American manufacturing plant. It converted the old form of the drug into a new polymorph, Form 2, that did not fight AIDS nearly as well. Abbott’s plant was contaminated, and it could no longer manufacture effective rintonavir. Abbott continued to successfully manufacture the drug in its Italian plant. Then American scientists visited, and that plant too was contaminated was contaminated and could henceforth only produce the ineffective Form 2. Apparently the scientists had carried some Form 2 crystals into the plant on their clothing.
Another instance of the “disappearing polymorph” may be the anti-depressant, Paxil (U.S. brand name for the chemical paroxetine hydrochloride). No, self-replicating Paxil doesn’t naturally spread into our brains and make people happy for free. It's not "happy goo." On the contrary, self-replicating Paxil converted, according to one of the parties in the ensuing lawsuit, an old, and now off-patent, form of Paxil into a new, patented form of Paxil. Once the new form, the hemihydrate form of Paxil, was created, its crystals started floating about, converting small fractions of the old form, anhydrous Paxil, into hemihydrate. Both forms of the drug work equally well as an anti-depressant, but it became impossible to manufacture the off-patent anhydrate without some of it being converted into the patented form. Call it "patent goo."
Apotex, a generic drug manufacturer, was all set up to manufacture the off-patent anhydrous generic Paxil when it discovered small fractions of it were being converted into the hemihydrate. They couldn’t remove the contamination. Smithkline, owner of the patent on the hemihydrate, sued them for patent infringement. Apotex argued that the hemihydrate form occurred naturally, so that Smithkline’s patent was invalid. Smithkline argued that it was a disappearing polymorph, that the hemihydrate form had not existed before they had created it in their labs, and that it was up to Apotex to remove the hemihydrate from its product or pay it a royalty. Apotex was unable to remove the hemihydrate and unwilling to pay a royalty.
Judge Richard Posner heard this case in the trial court and wrote an opinion that contains a good explanation of the self-replicating Paxil controversy. The Federal Circuit heard the appeal and decided that Smithkline’s patent on the hemihydrate was invalid as “inherently anticipated” because anhydrate naturally converts into hemihydrate. Normally, anticipation would require an actual reference describing the claimed chemical structure (in patent lingo that the hemihydrate was "taught in the prior art"). But Judge Rader held that inherent anticipation occurs when, more likely than not, an operation that is taught in the prior art would result in the claimed chemical. The anhydrate which was taught in the prior art would more than likely result in natural creation of some hemihydrate. Judge Gajarsa in concurrence argued that the drug was discovered not invented, making it unpatentable subject matter. Gajarsa’s opinion may have inspired the United States Supreme Court to raise the subject matter issue on its own (i.e., it had not been argued by the parties to the case) in Metabolite. The Supreme Court is considering whether to take the appeal on the self-replicating Paxil case as well.
The kula ring
 Just off the cost of New Guinea, Melanesians evolved (over thousands, and perhaps even tens of thousands, of years) a unique commercial institution known as the "kula ring" for the collectibles that circulated within it.
The unforgeably scarce kula collectibles doubled as "high power" money and mnemonic for stories and gossip. Many of the goods traded, mostly agricultural products, were available in different seasons, and so could not be traded in kind. Kula collectibles solved this double-coincidence problem as an unforgeabaly costly, wearable (for security), and circulated (literally!) money. Necklaces circulated clockwise, and armshells counter-clockwise, in a very regular pattern. By solving the double-coincidence problem an armshell or necklace would prove more valuable than its cost after only a few trades, but could circulate for decades. Gossip and stories that about prior owners of the collectibles further provided information about upstream credit and liquidity. In other Neolithic cultures collectibles, usually shells, circulated in a less regular pattern but had similar purposes and attributes.

Sunday, September 07, 2008
A letter from the industrial revolution

Images: Copper halfpenny minted by the Darbies' Coalbrookdale Company and celebrating the Iron Bridge.
Here's an interesting letter from the dawn of the industrial revolution. It was written in 1775 by Abiah Darby, mother of Abraham Darby (III) and wife of Abraham Darby (II), the son of Abraham Darby (I), who invented the process of smelting iron with coke made from coal. The Darby family were Quakers and produced several early industrialists and engineers. This small letter makes or implies several points that may have been crucial to the growth of industry that makes modern wealth possible:
* The importance of property rights and market prices in maintaining a sustainable balance between the supply and demand of wood. ("woods for charcoal became very Scarce and landed Gentlemen rose the prices of cord wood exceeding high"). Although wood became expensive, there remained a sufficient supply of wood for the buildings, mine works, wagons, rails, etc.
* The ability of people living with sufficient technology and secure property rights to bypass and surpass ecological limitations (in this case substituting coal for wood, and later due to this cheap iron-making process, iron and steel for wood).
* Decentralized money issue. Abiah points out that the remote area of Coalbrookdale, where coal and iron were available, still often operated as a barter economy. Thus apparently Abraham had to either coin tokens or open a bank to issue notes (common during this era) so that the Darbies could pay their workers.
* Darby II's invention of the iron-tracked railroad (improving the productivity of the horses by over six times and precursor to the later steam-powered railroad).
* The ability to securely establish large machine works and lay 20 miles of track out in the boondocks and not have them be torn up by trespassers and used for other purposes or confiscated or taxed into oblivion by local lords. In most of the rest of the world that could not be taken for granted.
* The use of atmospheric pressure (Papin/Savery/Newcomen) steam engines to drain the mines and supply water to the waterwheel pond. (The atmospheric engine apparently wasn't up to the job of directly powering the bellows for the blast furnaces; that came later with the Watt steam pressure engine). Steam engines allowed water to be pumped out of mines at a far greater rate, and thus allowed coal and iron mines to be dug far deeper, creating a large and inexpensive new supply of coal and iron.
The link is a Word document, which I don't recommend opening for security reasons, but I've copied the contents below:
http://www.umassd.edu/ir/Resources/MetalandMining/m2.doc
Mrs. Abiah Darby on developments in the Darby ironworks at Coalbrookdale, 1708-1763
Esteemed Friend,
Thy very acceptable favour of the 9th ulto. claim'd my earliest acknowledgments, which I should immediately have made, had not thy kind condescension in taking notice of my late honour'd Husband, and requesting to be inform'd of any circumstance which may be interesting relating him, caused my delay-to recollect what might occur concerning his transactions or improvements in the Manufactory of Iron, so beneficial to this nation. But before I proceed further, I cannot help lamenting with thee in thy just observation, " that it has been universally observed, that the Destroyers of mankind are recorded and remembered, while the Benefactors are unnoticed and forgotten". This seems owing to the depravity of the mind, which centres in reaping the present advantages, and suffering obscurity to vail the original causes of such benefits; and even the very names of those to whom we are indebted for the important discoveries, to sink into oblivion. Whereas if they were handed down to posterity, gratitude would naturally arise in the commemoration of their ingenuity, and the great advantages injoyed from their indefatigable labours-I now make free to communicate what I have heard my Husband say, and what arises from my own knowledge; also what I am inform'd from a person now living, whose father came here as a workman at the first beginning of these Pit Coal Works.
Then to begin at the original. It was my Husband's Father, whose name he bore (Abraham Darby and who was the first that set on foot the Brass Works at or near Bristol) that attempted to mould and cast Iron pots, &c., in sand instead of Loam (as they were wont to do, which made it a tedious and more expensive process) in which he succeeded. This first attempt was tryed at an Air Furnace in Bristol. About the year 1709 he came into Shropshire to Coalbrookdale, and with other partners took a lease of the works, which only consisted of an old Blast Furnace and some Forges. He here cast Iron Goods in sand out of the Blast Furnace that blow'd with wood charcoal; for it was not yet thought of to blow with Pit Coal. Sometime after he suggested the thought, that it might be practable to smelt the Iron from the ore in the blast Furnace with Pit Coal: Upon this he first try'd with raw coal as it came out of the Mines, but it did not answer. He not discouraged, had the coal coak'd into Cynder, as is done for drying Malt, and it then succeeded to his satisfaction. But he found that only one sort of pit Coal would suit best for the purpose of making good Iron. -These were beneficial discoveries, for the moulding and casting in sand instead of Loam was of great service, both in respect to expence and expedition. And if we may compare little things with great-as the invention of printing was to writing, so was the moulding and casting in Sand to that of Loam. He then erected another Blast Furnace, and enlarged the Works. This discovery soon got abroad and became of great utility.
This Place and its environs was very barren, little money stiring amongst the Inhabitants. So that I have heard they were Obliged to exchange their small produce one to another instead of money, until he came and got the Works to bear, and made Money Circulate amongst the different parties who were employed by him. Yet notwithstanding the Service he was of to the Country, he had opposers and ill-wishers, and a remarkable circumstance of awful Memory occurs; of a person who endeavour'd to hinder the horses which carried the Iron Stone and Coal to the Furnaces, from coming through a road that he pretended had a right to Oppose: and one time when he saw the horses going alone, he in his Passion, wished he might Never Speak More if they should Ever come that way again. And instantly his Speech was stopped, and altho' he lived Several years after yet he Never Spoke More!
My Husband's Father died early in life; a religious good man, and an Eminent Minister amongst the people call'd Quakers.
My Husband Abraham Darby was but Six years old when his Father died-but he inherited his genius-enlarg'd upon his plan, and made many improvements. One of Consequence to the prosperity of these Works was as they [were] very short of water that in the Summer or dry Seasons they were obliged to blow very slow, and generally blow out the furnaces once a year, which was attended with great loss. But my Husband proposed the Erecting a Fire Engine to draw up the Water from the lower Works and convey it back into the upper po6ls, that by continual rotation of the Water the furnaces might be plentifully supplied; which answered Exceeding Well to these Works, and others have followed the Example.
But all this time the making of Barr Iron at Forges from Pit Coal pigs was not thought of. About 26 years ago my Husband conceived this happy thought-tbat it might be possible to make bar from pit coal pigs. Upon this he Sent some of our pigs to be tryed at the Forges, and that no prejudice might arise against them he did not discover from whence they came, or of what quality they were. And a good account being given of their working, he errected Blast Furnaces for Pig Iron for Forges. Edward Knight Esqr a capitol Iron Master urged my Husband to get a patent, that he might reap the benefit for years of this happy discovery: but he said he would not deprive the public of Such an Acquisition which he was Satisfyed it would be; and so it has proved, for it soon spread, and Many Furnaces both in this Neighbourhood and Several other places have been errected for this purpose.
Had not these discoveries been made the Iron trade of our own produce would have dwindled away, for woods for charcoal became very Scarce and landed Gentlemen rose the prices of cord wood exceeding high-indeed it would not have been to be got. But from pit coal being introduced in its stead the demand for wood charcoal is much lessen'd, and in a few years I apprehend will set the use of that article aside.
Many other improvements he was the author of. One of Service to these Works here they used to carry all their mine and coal upon horses' backs but he got roads made and laid with Sleepers and rails as they have them in the North of England for carring them to the Rivers, and brings them to the Furnaces in Waggons. And one waggon with three horses will bring as much as twenty horses used to bring on horses' backs. But this laying the roads with wood begot a Scarcity and rose the price of it. So that of late years the laying of the rails of cast Iron was substituted; which altho' expensive, answers well for Ware and Duration. We have in the different Works near twenty miles of this road which cost upwards of Eight hundred pounds a mile. That of Iron Wheels and axletrees for these waggons was I believe my Husband's Invention.
He kept himself confined to the Iron Trade and the Necessary Appendages annex'd thereto. He was just in Ms dealings-of universal benevolence and charity, living Strictly to the Rectitude of the Divine and Moral Law, held forth by his great Lord and Saviour, had an extraordinary command over his own spirit, which thro' the Assistance of Divine Grace enabled to bear up with fortitude above all opposition: for it may seem very strange, so valuable a man should have Antagonists, yet he had. Those called Gentlemen with an Envious Spirit could not bear to see him prosper; and others covetious; strove to make every advantage by raising their Rents of their collieries and lands in which he wanted to make roads; and endeavour'd to stop the works. But he surmounted all: and died in Peace beloved and Lamented by many.
The principle of least authority
I've written an article on my application of the principle of least authority to the interpretation of legal language. I argue that the United States Constitution, according to its original meaning, instructs judges to construe federal statutes, regulations, executive orders, and other official acts, as well as the Constitution itself, to confer the least authority consistent with their language.
This article is based on a longer paper on the origins of the non-delegation doctrine I wrote for law school. That paper highlights a little-known debate on the non-delegation doctrine applied to the question of whether Congress could delegate the power to define postal roads. James Madison, among others, argued that this was an unconstitutional delegation of legislative power to the executive.
This article is based on a longer paper on the origins of the non-delegation doctrine I wrote for law school. That paper highlights a little-known debate on the non-delegation doctrine applied to the question of whether Congress could delegate the power to define postal roads. James Madison, among others, argued that this was an unconstitutional delegation of legislative power to the executive.
Subscribe to:
Posts (Atom)